1. Home
  2. Property Finance
  3. Owner-occupied commercial mortgages
Long-term lending

Owner-occupied commercial mortgages

An owner-occupied commercial mortgage funds a property that your own business will trade from. Because no third-party rent pays the loan, the lender is essentially asking whether your business can afford to own its premises. Trading profit, cash flow and the resilience of the business carry the application, while the building provides security behind it.

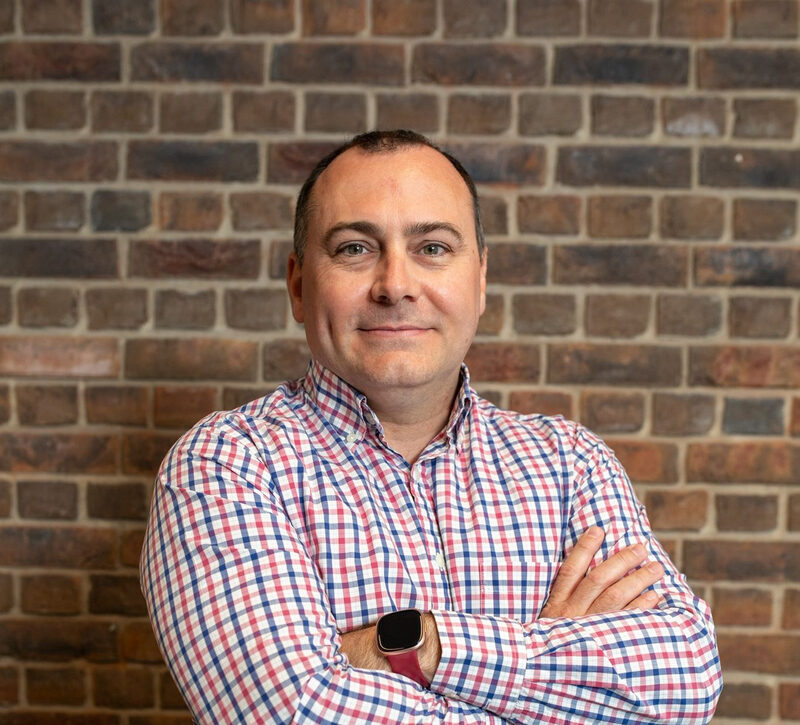
Graham Nash, Commercial Finance Director at Sorbus Finance
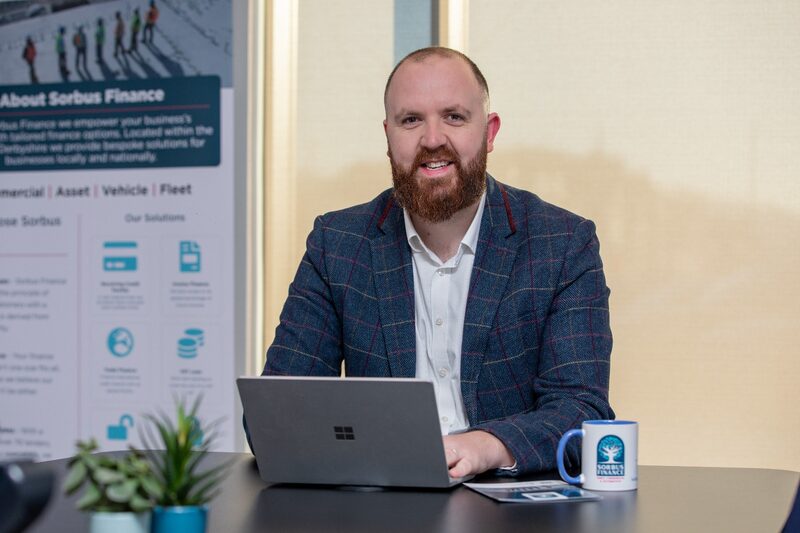
Arran Turner, Managing Director at Sorbus Finance

Speak with Graham or Arran

Affordability comes from trading

Lenders typically review filed accounts, current management figures and sometimes forecasts. They look at profit after existing borrowing and drawings, and ask whether the new payments fit comfortably. Rent you stop paying can help the story, but lenders will usually still want evidence that the business itself generates enough.

A dip in one year is not necessarily fatal if you can explain it with evidence. Unexplained losses, rising debts or tax arrears are harder.

Who owns the building

Some owners buy through the trading company, others through a separate property company or personally, then lease the building to the business. Each route has tax, legal and lender consequences. A separate owning entity with a lease to the trading business may make the case look more like an investment, so speak to your accountant before choosing a structure.

Specialist premises

Buildings designed for one purpose, such as certain leisure, care or hospitality properties, may be valued with reference to the business that operates in them. That can make the lender more cautious, because the value of the property and the value of the trade are linked.

Hypothetical example, not a real client: a veterinary practice wants to buy its converted clinic. A lender may consider both the clinical trade and how easily the building could be used by a different occupier.

Weighing ownership honestly

Owning premises brings control, but also repair liabilities, insurance, business rates responsibility and concentration of risk: a struggling business may find its home and its debt tied together. Owning is not automatically better than renting; it depends on your plans, cash reserves and appetite for property risk.

How lenders read your accounts

A lender may ask for an explanation of the profit figure rather than relying on it alone. Identify non-recurring costs, such as a one-off legal bill, and income that may not continue, such as a large contract that has ended. Do not assume a lender will accept a proposed adjustment. Explain directors’ drawings and dividends too, because they affect cash available to pay a mortgage.

Seasonality matters too. A garden centre, a holiday business or a contractor paid in stages can look very different month to month. Explaining your trading pattern, and showing cash flow across a full cycle, helps a lender understand that a quiet quarter is normal rather than a warning sign.

Moving from renting to owning

If you currently lease the premises you want to buy, check what your lease says about ending early and any dilapidations liability, which may fall away or be negotiated as part of the sale. If you are relocating, allow for a period of paying both rent and mortgage, fit-out costs and possible disruption to trade while you move. Lenders may ask how you will handle that overlap.

Planning for growth

Think about whether the building will still suit you as the business changes. Space for extra staff, storage, parking or equipment matters more once you own, because moving later means selling, which takes time and money.

Your property may be repossessed if you do not keep up repayments on a loan secured on it. Sorbus Finance is a broker, not a lender. Finance is subject to lender criteria, status, valuation and affordability. We work with a panel of lenders, not the whole market, and do not promise a rate, fee level or outcome.

Before you apply

Preparation checklist

  • Prepare recent filed accounts and up-to-date management accounts.
  • Note any one-off costs or exceptional items that distort profit.
  • Decide, with your accountant, which entity will own the property.
  • Check the building suits your future operations, not just today.
  • Budget for survey, legal work, tax and fit-out alongside the deposit.
  • Consider how payments would be met in a weaker trading year.
Questions

Common questions

Does my current rent count towards affordability?

It can support the case, but lenders usually still assess whether the business profits cover the new borrowing on their own terms.

Can I buy through a separate property company?

Often yes, with a lease to your trading business. Lender approach and tax effects vary, so take accounting advice first.

Will lenders lend on specialist trading premises?

Some will, but criteria can be tighter because the value may depend on the trade. Expect more scrutiny of the business.

Do I need a personal guarantee?

Many lenders ask for one from directors. Get independent legal advice on what you would be committing to.

Can I let part of the building?

Possibly, but tell the lender. Partial letting can change how the case is assessed and, if any part is residential, regulation could become relevant.

Is ownership a guaranteed saving over renting?

No. Ownership brings costs and risks renting does not. Model both honestly before deciding.

Sources

Independent references

Research checked 21 October 2026. Third-party references for context; they do not review or endorse this page.

Who you could speak to

Graham Nash, Commercial Finance Director at Sorbus Finance

Graham Nash

Commercial Finance Director

Business loans, cash flow and wider commercial funding

Profile
Arran Turner, Managing Director at Sorbus Finance

Arran Turner

Managing Director

General commercial finance and how Sorbus works

Profile
  1. STEP 1

    A conversation with a broker

    You talk to a real Sorbus broker about the business, the purpose and what is affordable. No application at this stage.

  2. STEP 2

    Credit placement

    If you choose to go further, we prepare the case and decide which lenders on our panel of 150+ are worth approaching.

  3. STEP 3

    Lender assessment

    The lender, not Sorbus, underwrites and makes the credit decision. Approval is never guaranteed.

  4. STEP 4

    Documentation

    If a lender offers terms and you accept, we help coordinate agreements and payout paperwork with you.

Every step after the first is optional. You can stop after the conversation. Sorbus is a broker, not a lender.

Client journey

Explore real client journeys

Read how real businesses approached a funding goal, what Sorbus arranged and what happened next.

Browse anonymised case studies
Enquire about Owner-occupied commercial mortgages

Start with a conversation

Tell us a little about what you need and who you would like to speak to. No obligation, no credit check at this stage. We aim to respond within one business day, Monday to Friday, 9am to 5:30pm.

A preference, not an appointment. We pass it on where we can. We aim to respond within one business day, Monday to Friday, 9am to 5:30pm. This is an aim, not a guaranteed callback time.

We will use your details to respond to your enquiry. We may share information with our principal, lenders and service providers where necessary, or where required by law, as explained in our Privacy Policy. Marketing emails are optional and depend on your separate choice.

Prefer to call?

Speak directly to an adviser Monday–Friday, 9am–5:30pm.

01246 383500

Free call. No obligation.

Unique to Sorbus Finance

Optional: Business Finance Health Check

Before applying for owner-occupied commercial mortgages, understand your lending readiness, resilience score, and exit strategy, in under 5 minutes.

Take the short Health Check

Free · No credit check · Not required before you talk

Want the full picture? The full fact-find is longer and also optional.

Sending this is an enquiry, not an application or approval.

01246 383500